Walk past any tea stall in a small town and there’s a QR code taped to the counter, usually slightly crooked. Nobody sat the owner down and explained fintech to him. Paying by phone was just less hassle than hunting for change.
I think that’s what really changed fintech in India. The popular apps get noticed, but the bigger change happened behind the scenes. UPI, digital KYC, GST data and bank statements that software could read made it easier to build new financial services. A lot of what we see today came after these “systems” were in place.
Disclaimer: Please keep in mind that the “rules” and “product terms” in this space change often, so check anything below with the RBI or your provider before you act on it.
What digital banking does for a business
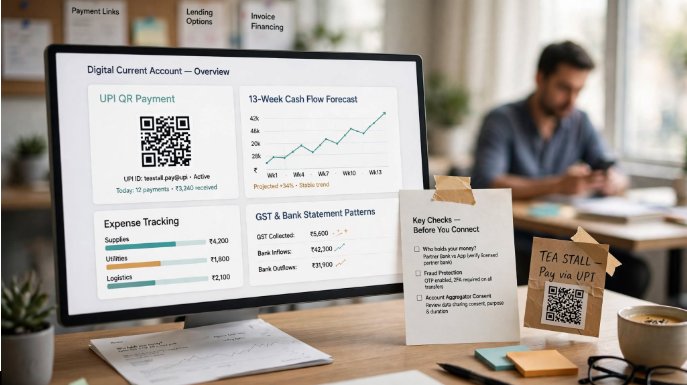
Ten years ago, you’d have to visit a bank more than once to open a current account and carry photocopies of your documents. Now, you can often open one “online” in a day. You can also “send payment links”, pay vendors in bulk and check transactions on one dashboard.
The gains for a small firm are mostly boring ones. Money arrives in seconds. Reconciliation, the job of matching payments against invoices, stops eating a day every month. You can check the balance at midnight without calling anyone.
One thing worth knowing if you’re considering a neobank: many are apps sitting on top of a partner bank. That’s fine, but find out which bank actually holds your money. The app is the interface, and the licensed bank is where your protection comes from.
For a young startup, the biggest benefit is that you can run finance on very little. A founder with a business account and a decent accounting tool can get through the first year without a full-time finance hire. You’ll still want a chartered accountant for tax and compliance. That part doesn’t go away.
Where AI helps in financial technology
Mostly in unexciting places.
Chatbots handle failed transactions and statement requests well enough. They’re maddening when your problem is unusual, so when you pick a provider, check how easily you can reach a human. It tells you more than any feature list.
Fraud detection is the better use. Models watch for strange behaviour, like a payment from a city you’ve never been in or twenty small transfers in ten minutes. No team could review that volume by hand. But these systems get it wrong both ways. They miss clever fraud and they freeze honest payments, and I’ve seen small businesses lose a day of sales to an automatic block. Keep a second payment route available.
The third use, analysing your own data, gets the least attention and probably pays off most. Which customers pay late? Which product looks busy but earns nothing? Most owners could answer from the data they already have.
Cash flow for startups
Cash flow is where young companies get hurt, and fintech tools help in a few practical ways.
Say a design studio invoices “₹3 lakh” and the client takes “45 days” to pay. A payment link, an automatic reminder on “day 30” and a partial advance upfront can shave weeks off that. Chasing is awkward, so let software do it.
Spend tracking is next. Connect cards and bank accounts to an expense tool and you’ll see where money goes. Nearly everyone finds subscriptions nobody uses.
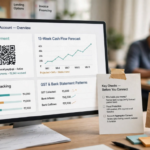
Then there’s the 13-week cash forecast. It’s a sheet showing expected money in and out for each week, and it can flag a gap two months before you’d feel it. Several finance tools can build it from live data. Working capital becomes easier to manage once receivables, payables and balance sit on one screen.
None of this fixes thin margins. It just shows you the problem earlier, and that’s often enough to act in time.
Digital lending
A small business may get turned down by a bank for not having enough collateral or a long credit history. Online lenders started offering other options, such as working capital loans, invoice financing and short-term credit. Some can approve these loans within a day.
What changed is how they judge you. Instead of asking only for property papers and old returns, many look at bank statement patterns, GST filings and UPI inflows. A shop with steady daily takings but nothing to mortgage can now get credit it was once refused. That’s a real step forward for financial inclusion.
The catch is cost. Once processing fees, penalties and short repayment windows are added, some digital loans are expensive. Look at the total cost, not the monthly rate in the advert. RBI rules require lenders to share a key facts statement with the annual percentage rate and all charges. You should ask for it before taking a loan. If the “lender” won’t give clear details, look elsewhere. Also check that the “lender” is a bank or an RBI-registered NBFC and that the app is linked to that lender.
My rule of thumb is to borrow for something that earns money, such as stock or equipment, and not to cover losses.
Fraud, privacy and compliance
More of your business online means more to protect.
The everyday threats are simple. A fake payment link. A message that looks like it’s from your bank. A caller claiming to be a bank executive who needs one OTP. Small businesses lose money to these constantly, and the fixes are unglamorous: never share an OTP, confirm any payment request on a second channel, turn on two-factor authentication, and give each person their own login with limited approval rights.
If your business collects customer data, you’re responsible for it. The “Digital Personal Data Protection Act, 2023” puts duties on businesses that handle personal data, and the detailed rules have been arriving in stages, so get legal advice on where you stand.
A fintech startup can’t just start handling money. It needs the right licence or an arrangement with a regulated company.
Compliance feels like a cost when you’re small. It’s cheaper than the alternative.
What’s coming next
Three things look likely to matter.
Open banking, in India’s version. The “Account Aggregator” framework already lets you share bank and financial data with approved providers, with your consent, and no paperwork. As banking APIs spread, accounting, payroll and lending tools can plug straight into your accounts, which makes comparing offers and switching providers easier.
Embedded finance, which means financial services tucked inside products that aren’t banks: a loan option in a seller dashboard, insurance at checkout. It’s convenient for customers and a new revenue source for companies, though touching money brings compliance duties.
And AI-led credit scoring and advice, where the open question is how well providers handle mistakes and bias. Expect regulators to keep a close eye on it.
If you want to see how this plays out across banking, startups and the wider economy, the business and fintech developments on Malik Times are a handy way to keep up.
Quick answers
What is the fintech industry in India?
Companies that use technology to deliver financial services: payments, online banking, lending, insurance and investing apps.
Are digital loans safe?
They can be, if the lender is regulated and you’ve read the full cost and repayment terms.
How do I protect my business from payment fraud?
To protect your business, we’d recommend you to never share OTPs, verify requests on a second channel, use two-factor authentication and limit who can approve payments.
One last thing
The tools are good, and for small businesses they’re a real improvement over what existed before. But a faster way to pay, borrow and be paid is also a faster way to lose money if you’re careless. Know who holds your money, read what you sign, and keep your own numbers in front of you.
More on business, banking and technology is at https://maliktimes.in/business-news/ and in Startup News on Malik Times.
